TLDR
- Account verification and bank data connectivity are two different problems. Most teams treat them as one and overpay for capabilities they never use.
- The verification method matters more than the data coverage. Instant OAuth-based auth, micro-deposit confirmation, and real-time balance checks each carry different fraud risk and ACH return profiles.
- Checking a balance before initiating an ACH pull is the single most impactful step to cut NSF-driven returns. Not every API in this list supports real-time balance reads.
- Pricing structures vary widely. Some providers charge per verification call, others bundle it into a platform fee, and a few tier by auth method, which means the cheapest headline price is often not the cheapest total cost.
- Sponsor slots in this article: Plaid Auth, MX, Sardine, Yodlee, Finicity. All five are evaluated using the same criteria as every other entry.
The best account verification API for most US fintech teams is Plaid Auth for instant OAuth-based verification with broad bank coverage, Finicity for lending and FCRA-permissible use cases, and Sardine for teams that need fraud signals layered on top of account confirmation. The right choice depends on which auth method your ACH processor accepts, whether you need real-time balance checks before payment initiation, and how aggressively you want to screen for synthetic bank accounts at enrollment.
Why Account Verification Is Not the Same as Bank Data Connectivity
Teams evaluating open banking APIs often conflate two distinct capabilities. Bank data connectivity pulls transaction history, categorizes spending, and feeds underwriting models. Account verification confirms that a bank account exists, belongs to the user claiming it, and has funds available before a payment moves. They sometimes share infrastructure, but they solve different problems.
The distinction matters for ACH specifically. A failed ACH return costs between $2 and $5 in raw bank fees, a range consistent with published NACHA guidance and standard bank fee schedules, before you account for the operational overhead of resolving it. Unauthorized returns, where a user claims they never authorized the debit, can trigger NACHA compliance reviews at return rates above 0.5%. A real-time balance check at payment initiation catches the most common failure mode: insufficient funds. An account ownership check catches the second most common: wrong account number or fraudulent enrollment.
If your primary concern is connectivity breadth for data aggregation, the 9 Best Plaid Alternatives for Bank Data Connectivity covers that angle. This article focuses specifically on the verification layer: how each API confirms account ownership, what balance data it returns, and where each one fits in a US payment stack.
The FintechSpecs Auth-Method Hierarchy: How Verification Methods Rank by Fraud Risk and Speed
Before comparing vendors, it helps to understand that not all verification is equal. We categorize the main methods into four tiers based on the trade-off between speed, conversion, and fraud resistance.
Tier 1: Instant OAuth / Token-Based Auth. The user logs into their bank directly inside a hosted flow. The API returns account and routing numbers with ownership confirmed by the bank. No credentials stored. Fastest conversion, lowest fraud surface, but requires the bank to support OAuth. Coverage gaps exist at smaller credit unions and community banks.
Tier 2: Credential-Based Instant Verification. The user enters their online banking username and password into a hosted widget. The aggregator scrapes or uses a direct connection to return account details. Faster than micro-deposits but carries higher risk from credential exposure and bank blocking. CFPB Section 1033 rulemaking is putting pressure on screen-scraping paths, which makes this tier riskier to build on long-term. See the Section 1033 open banking compliance guide for what this means for your stack.
Tier 3: Database / Tokenized Verification. Account and routing numbers are matched against a database of known account-holder records without the user logging in anywhere. Useful for low-friction B2B onboarding where the business has account data on hand. Lower conversion friction, but ownership confirmation is probabilistic, not cryptographic.
Tier 4: Micro-Deposit Verification. Two small deposits land in the account, typically within one to three business days depending on the receiving bank’s processing schedule. The user confirms the amounts. Slowest, no real-time balance data, but accepted by nearly every bank and has the longest compliance track record. Still the fallback for accounts that fail Tier 1 and Tier 2.
How to Run a Balance Check Before an ACH Pull
A balance check API call returns one of three things depending on the provider: a raw current balance figure, a binary “sufficient/insufficient” flag against a threshold you supply, or a combination of current and available balance with a timestamp. The timestamp matters. A balance read at 8 a.m. does not reflect a noon withdrawal. Real-time balance APIs that connect via direct bank APIs are more reliable than those built on overnight data refresh cycles.
To illustrate the cost dynamic: consider a lending platform pulling $3,200 weekly from borrower accounts. Without a pre-debit balance check, even a 2% NSF return rate on $1M monthly in ACH volume generates roughly $20,000 to $50,000 in return fees and operational cost before accounting for the collections cycle that follows, based on the $2 to $5 per-return fee range noted above, scaled across return volume. This is a hypothetical scenario to show the cost structure, not a verified case study. With a real-time balance check at the point of scheduling, that return rate typically drops. Plaid Signal, for example, provides a predictive score rather than a raw balance; Finicity’s account verification endpoint returns current and available balance figures directly from bank connections.
Not every provider in this list returns a live balance figure. Some return a score, some return a balance, and some return nothing on the balance dimension at all. The comparison table below marks each one explicitly.
Comparison Table: 11 Account Verification APIs by Method, Balance Check, and Use Case
| Provider | Auth Methods | Real-Time Balance Check | Micro-Deposit Option | Primary Use Case Fit | Public Pricing |
|---|---|---|---|---|---|
| Plaid Auth | OAuth, credential, database | Via Plaid Signal (score) / Balance product (raw) | Yes (same-day available) | Consumer fintech, neobanks, lending | Not publicly listed |
| MX | OAuth, credential | Yes, via account data connections | No native option | FI-facing, credit unions, banks | Not publicly listed |
| Sardine | OAuth, database, device signals | Yes, with fraud scoring overlay | No | Fraud-sensitive enrollment, crypto, lending | Not publicly listed |
| Yodlee (Envestnet) | OAuth, credential, FastLink | Yes | No native option | Wealth management, PFM, lending | Not publicly listed |
| Finicity (Mastercard) | OAuth, credential | Yes (current + available balance) | Yes | Mortgage, lending, FCRA use cases | Not publicly listed |
| Stripe Financial Connections | OAuth (bank-direct) | Yes (balance endpoint) | No | Stripe-native stacks, SaaS billing | Verify: $1.50/account (as of Stripe’s public pricing page, last checked October 2024) |
| Quiltt | OAuth, credential (via Plaid/MX/Finicity) | Depends on underlying connection | No native | Consumer apps needing multi-aggregator fallback | Not publicly listed |
| Dwolla | OAuth (via Plaid/Finicity integration), micro-deposit | Via integrated provider | Yes (native) | ACH payment platforms, marketplaces | Not publicly listed |
| Alloy | Orchestrated (Plaid, Finicity, others) | Via connected data source | No native | Identity decisioning with bank verify layer | Not publicly listed |
| Akoya | OAuth (FDX-standard, direct bank APIs) | Yes | No | Bank-direct OAuth, no screen-scraping | Not publicly listed |
| Trustly | OAuth (bank-direct) | Yes | No | High-volume ACH pay-by-bank, iGaming, insurance | Not publicly listed |
Which Account Verification API Should You Actually Use?
Plaid Auth: Best overall for US consumer fintech
Plaid Auth covers the widest set of US financial institutions for instant account verification. The OAuth path, which Plaid calls its “same-day micro-deposit” and “instant match” flow depending on bank support, returns account and routing numbers confirmed by the institution. Plaid’s Balance product returns current and available balance figures. Plaid Signal returns a machine-learning score predicting return probability, which is more operationally useful for most ACH schedulers than a raw balance read.
The main reason to look elsewhere: Plaid’s contract structure at meaningful volume. Pricing is negotiated, not public, and teams report minimum commitments that make it expensive for early-stage companies. The Stripe Financial Connections comparison at Stripe Financial Connections vs. Plaid covers that cost angle in detail.
Finicity: Best for lending and FCRA-permissible use cases
Finicity, now part of Mastercard, was built primarily for mortgage and lending workflows. Its account verification endpoint returns current and available balance data alongside account ownership confirmation. Critically, Finicity’s data is FCRA-permissible, meaning it can be used in adverse action scenarios without triggering additional compliance obligations that trip up teams using general-purpose aggregators for credit decisions. If your product involves underwriting, Finicity’s compliance posture is a meaningful differentiator versus Plaid Auth.
Sardine: Best for fraud-heavy enrollment contexts
Sardine approaches account verification differently from the data aggregators. Rather than leading with bank connectivity, Sardine layers device intelligence, behavioral biometrics, and network-based fraud signals on top of the account data to return a risk score at enrollment. For crypto exchanges, lending apps, or any product with a synthetic identity or money mule problem at onboarding, Sardine’s combined signal is more useful than a clean account number alone. Teams that treat fraud and account verification as separate budget lines often discover that Sardine consolidates both. The fraud detection tool comparison covers Sardine in its broader risk context.
MX: Best for financial institution partnerships
MX skews toward bank and credit union deployments rather than startup-facing integrations. Its account verification layer integrates with its data enrichment and financial wellness products, making it most relevant if you are building inside a financial institution’s environment or selling to one. MX’s coverage at smaller FIs, particularly credit unions, tends to outperform Plaid at that segment. For a pure startup building a consumer app, MX’s commercial model and integration overhead typically favor Plaid.
Yodlee: Best for established PFM and wealth workflows
Yodlee, owned by Envestnet, has the longest operating history of any aggregator in this list. Its FastLink widget handles account connection and verification in a single hosted flow. Coverage is broad but the developer experience is widely described as dated compared to Plaid or Stripe Financial Connections. The strongest fit is wealth management platforms, PFM tools, and teams already inside the Envestnet environment where Yodlee integration is a natural extension rather than a greenfield choice.
Stripe Financial Connections: Best for Stripe-native billing stacks
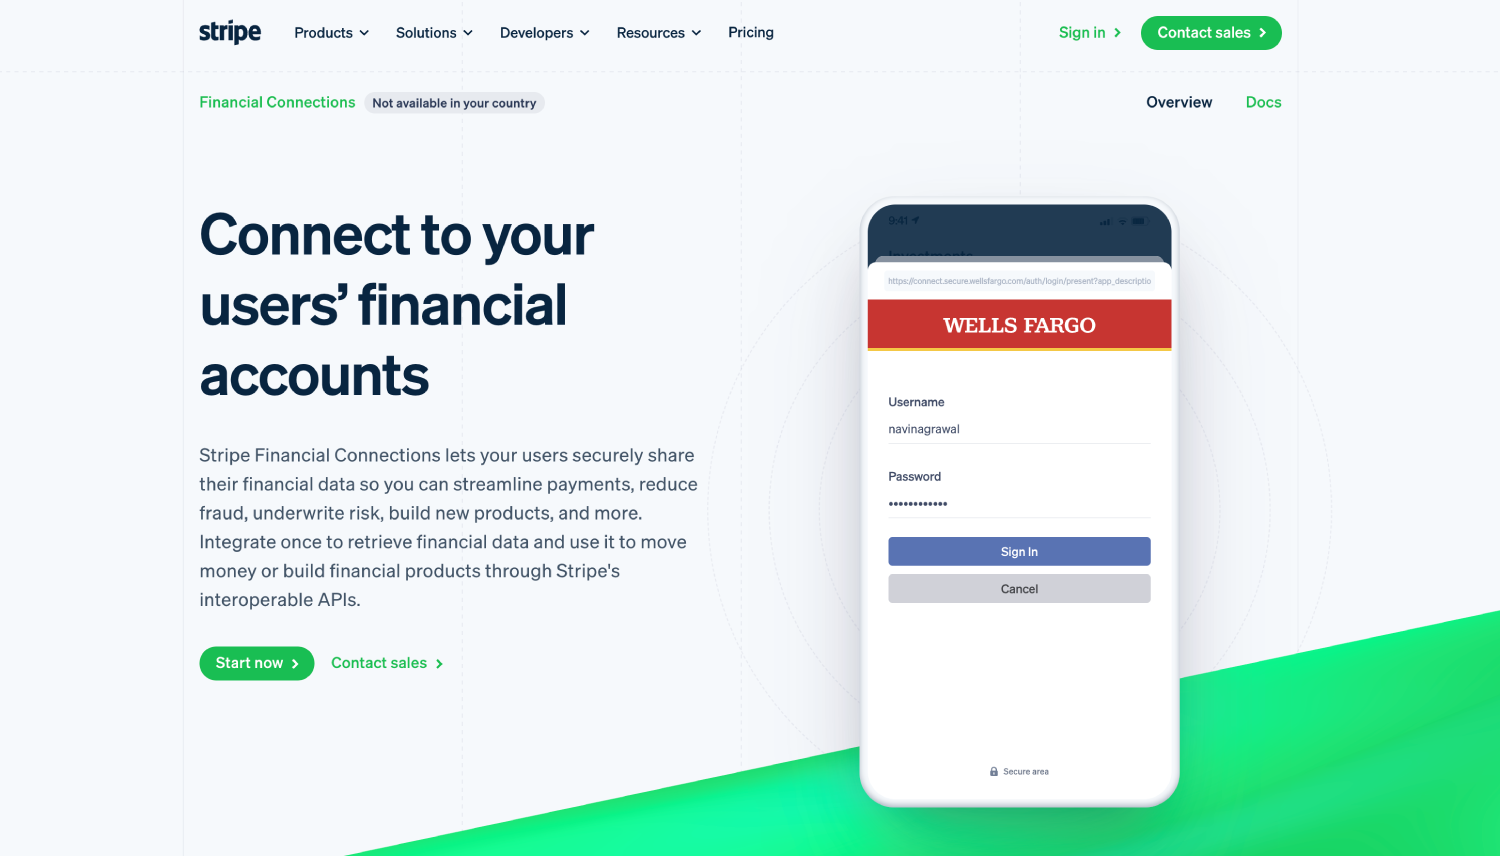
Stripe Financial Connections charges $1.50 per verified account as of their public pricing page (last checked October 2024, confirm current pricing directly with Stripe before contracting), which is one of the few transparent per-call prices in this category. The OAuth path works cleanly within the Stripe Dashboard for ACH Direct Debit setup. If your stack already runs on Stripe and you are verifying accounts for ACH billing, the integration overhead of adding a separate verification provider rarely justifies the potential savings at moderate volume. At high volume, the $1.50 per-account cost may exceed a negotiated Plaid contract rate.
Akoya: Best for teams that need pure OAuth with no screen-scraping risk
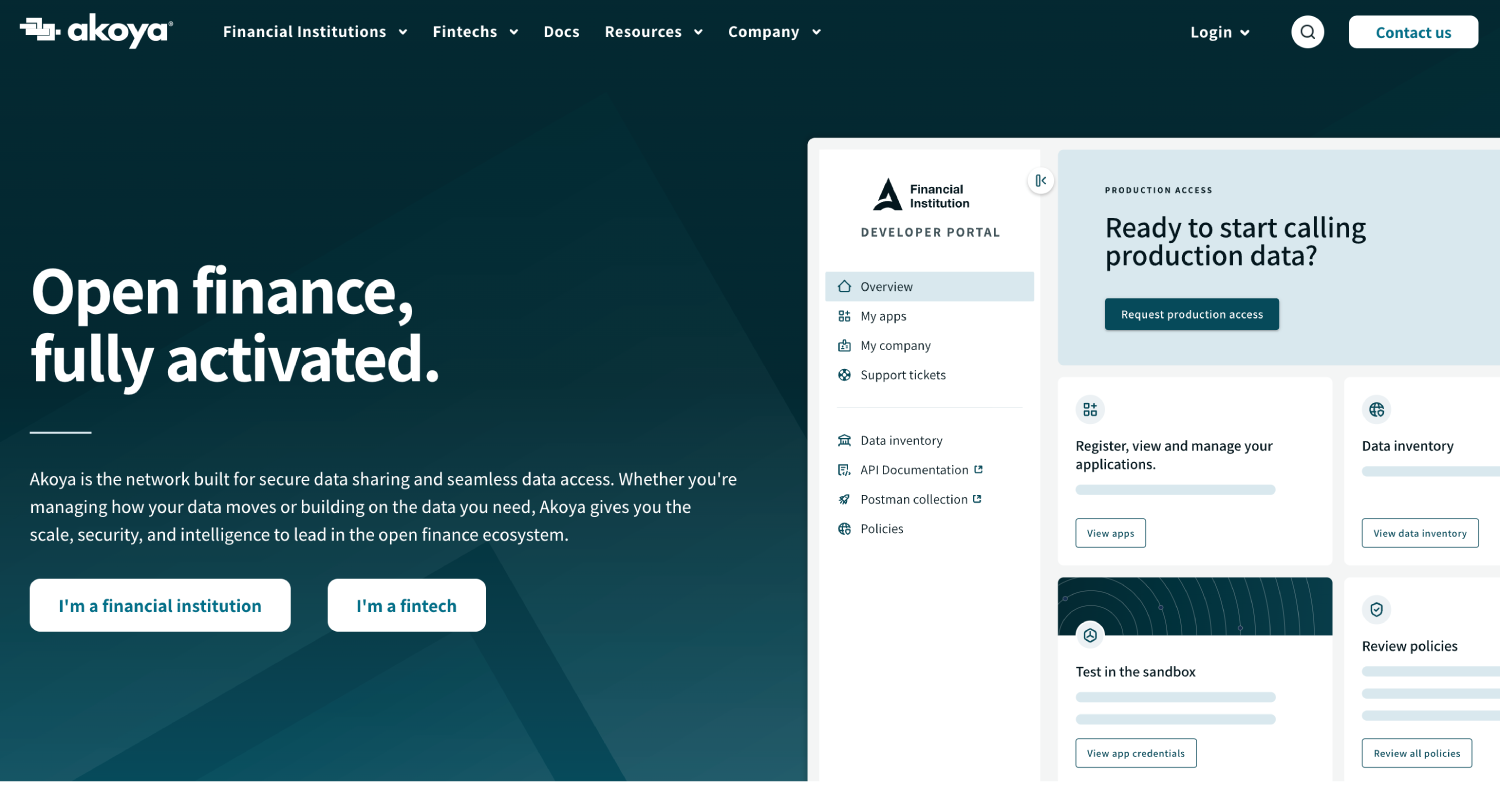
Akoya operates as a data access network built on FDX-standard OAuth APIs connected directly to bank systems. There is no credential-based fallback and no screen-scraping path. This matters because bank blocking of scrapers is an operational risk some teams underweight until it happens. Akoya’s coverage is narrower than Plaid but every connection is bank-sanctioned. For teams with Section 1033 compliance sensitivity, Akoya’s architecture is cleaner to defend to auditors.
Trustly: Best for high-volume pay-by-bank ACH
Trustly combines account verification with payment initiation through its pay-by-bank network. Rather than simply returning verified account credentials for your own ACH submission, Trustly handles the payment rail too. For iGaming, insurance premium collection, or high-volume consumer ACH use cases where you want a single vendor handling both verification and payment, Trustly’s model reduces integration surface. The trade-off is less flexibility if you want to route through your own ODFI relationship.
Quiltt: Best for multi-aggregator fallback coverage
Quiltt sits as an abstraction layer above Plaid, MX, and Finicity, routing connection attempts to whichever aggregator has the best coverage for a given institution. This is useful if your user base spans institution types where no single aggregator wins. The verification capability inherits from the underlying provider, so Quiltt’s value is routing and developer experience, not a proprietary verification method. Teams that have already negotiated contracts with multiple aggregators may find they can replicate Quiltt’s function without the additional layer.
Dwolla: Best for ACH platforms that want verification and payment bundled
Dwolla offers account verification as part of its ACH payment platform, integrating with Plaid and Finicity for instant verification and offering native micro-deposit verification as a fallback. The primary reason to use Dwolla’s verification is that it is embedded in the same platform handling your ACH moves, reducing the reconciliation surface between a verification event and a subsequent payment. Teams that need ACH payment API capabilities alongside verification should weigh Dwolla against building their own verification-plus-processor stack. The ACH payment API comparison covers Dwolla in more depth.
Alloy: Best for identity decisioning platforms that include bank account confirmation
Alloy is an identity orchestration platform that can include bank account verification as one signal in a broader decisioning workflow. It connects to Plaid, Finicity, and other data sources and lets you define pass/fail logic across all signals in one rule engine. If you are already evaluating Alloy for KYC and onboarding orchestration, extending it to account verification reduces vendor count. Alloy is not the right choice if account verification is your only problem and you have no existing identity orchestration layer to connect it to.
What to Ask Before Signing Any Account Verification API Contract
Coverage rate by institution type. Ask specifically: what percentage of your target user base’s banks support OAuth versus credential-based fallback versus database matching? A 95% coverage claim that is 40% credential-based is a different risk profile than 95% OAuth-based. Get the breakdown in writing.
Balance data freshness. If the use case is a pre-debit balance check, ask whether the balance endpoint reads from a live bank API call at request time or from a cached data pull from the previous night’s batch. Cached balance data for a same-day payment decision is operationally dangerous.
NACHA compliance support. Instant verification vendors should be able to confirm that their output satisfies NACHA’s WEB Debit Account Validation Rule, which requires that account validation be performed before the first ACH debit in a web-initiated context. Some providers explicitly certify this; others leave it to the customer to confirm.
What happens at micro-deposit fallback. Even OAuth-heavy providers fall back to micro-deposits for some institution coverage gaps. Understand the user experience your customers see when they hit that fallback path, and whether it extends enrollment time in ways that increase drop-off. The fintech onboarding drop-off analysis covers how verification steps affect completion rates.
Frequently Asked Questions
What is an account verification API?
An account verification API confirms that a bank account exists, is owned by the person providing it, and in some cases has sufficient balance to support a payment. It typically returns verified account and routing numbers, sometimes with ownership metadata and balance data. The output is used to reduce ACH return rates, prevent fraudulent account enrollment, and satisfy NACHA’s WEB Debit Account Validation Rule before initiating electronic payments.
How does instant account verification work?
Instant account verification uses one of three methods: OAuth, where the user authenticates directly with their bank and the bank confirms account ownership to the API; credential-based aggregation, where the user provides banking credentials to a hosted widget that retrieves account data; or database matching, where provided account numbers are matched against a known record set. OAuth is the most secure and carries the lowest fraud risk. Micro-deposit verification is the traditional fallback when instant methods fail or are unsupported by a given bank.
Which account verification API works best for ACH payments?
Plaid Auth is the most commonly used for US consumer ACH because of its institution coverage and Signal product for return risk scoring. Finicity is the stronger choice for lending or FCRA-regulated contexts. Stripe Financial Connections works well if your ACH payment processing already runs through Stripe. Trustly combines verification with payment initiation, which fits high-volume pay-by-bank use cases where you want a single vendor across both steps.
Can a balance check API prevent ACH returns?
A real-time balance check can reduce NSF-driven ACH returns by confirming available funds before initiating a debit. It does not eliminate returns entirely: a user could withdraw funds between the check and the debit settlement window, and it does not catch unauthorized return claims. Plaid Signal, Finicity’s balance endpoint, and Stripe Financial Connections all offer balance data. The key variable is whether the balance read is live at request time or pulled from a cached overnight batch, which varies by provider and by bank connection type.
What is the NACHA WEB Debit Account Validation Rule?
NACHA’s WEB Debit Account Validation Rule requires that originators validate a consumer account before initiating the first ACH debit on a web-initiated (WEB) entry. Validation must use a commercially reasonable method, which NACHA has clarified includes third-party instant verification services, micro-deposit confirmation, and prenote processes. Most major account verification APIs explicitly certify compatibility with this rule. Teams should request written confirmation from their vendor rather than assuming compliance based on marketing language.
How is micro-deposit verification different from instant account verification?
Micro-deposit verification involves sending two small deposits (typically under $0.50 each) to the account and asking the user to confirm the exact amounts. Completion time depends on the receiving bank’s processing schedule and is typically one to three business days, though some banks process faster. Instant account verification uses OAuth or credential connections to confirm ownership in seconds. Micro-deposits carry no fraud risk from credential exposure and are universally supported by US banks, but the time delay increases enrollment abandonment rates. Most providers offer instant verification with micro-deposit as an automatic fallback.
Does Sardine replace Plaid for account verification?
Sardine does not replace Plaid for raw account and routing number retrieval. Sardine’s account verification capability works alongside its fraud signals to produce an enrollment risk score. Teams typically use Plaid or Finicity for the account data layer and Sardine for the fraud risk layer, though Sardine can also retrieve account ownership data through its own connections. The two are complementary more often than they are substitutes, unless your primary concern is fraud at enrollment rather than pure account confirmation.
What is the difference between bank data connectivity and account verification?
Bank data connectivity retrieves transaction history, account balances over time, and categorized spending data for purposes like underwriting, PFM, and financial planning. Account verification confirms ownership and validity of a specific account number for a payment or enrollment event. They often use the same underlying bank connection infrastructure, but they serve different compliance requirements, different use cases, and sometimes different API products within the same vendor. Paying for full connectivity when you only need verification typically means overpaying.
The Clearest Way to Pick
Most teams spend weeks comparing aggregator coverage maps when the real variable is auth method. If the majority of your users bank at top-20 US institutions, every provider in this list covers them. The differentiation lives in what happens at the 15% of users who bank elsewhere, how the fallback flow is presented, and whether the balance data you receive is live enough to trust before a same-day ACH pull.
For a team building a US consumer product with ACH at the core, start with Plaid Auth and evaluate Signal for the return risk layer. For a lender needing FCRA-compliant verification with real balance data, Finicity is the cleaner choice. For any product where fraudulent enrollment is the primary threat rather than payment failure, Sardine’s combined signal justifies evaluation even if it sits alongside a separate aggregator connection.
The hidden cost in this category is not the per-verification fee. It is the ACH return fees, compliance overhead, and user drop-off from a verification flow that adds too many steps. The right API minimizes all three simultaneously. Pick the one that fits your auth method requirements first, then optimize for balance check freshness, and let pricing negotiation follow from there rather than lead it.